


Quick answer: As of October 2026, the average 30-year mortgage runs about 7.3 percent, and nationally the data describes fewer prospective buyers, a slower sales pace, and softer price growth than earlier years. Local markets differ. For a Central Pennsylvania landlord this is planning information, not a reason to sell or hold. PAC Financial in Harrisburg helps owners read it calmly, with their tax professional at the table. Call (717) 564-6400, ext. 181.
If you locked your mortgages years ago, a 7 percent headline can feel like someone else's problem. It is not. Your eventual buyer borrows at today's rate, or prices the deal as if they did, and your exit price lives inside their monthly payment.
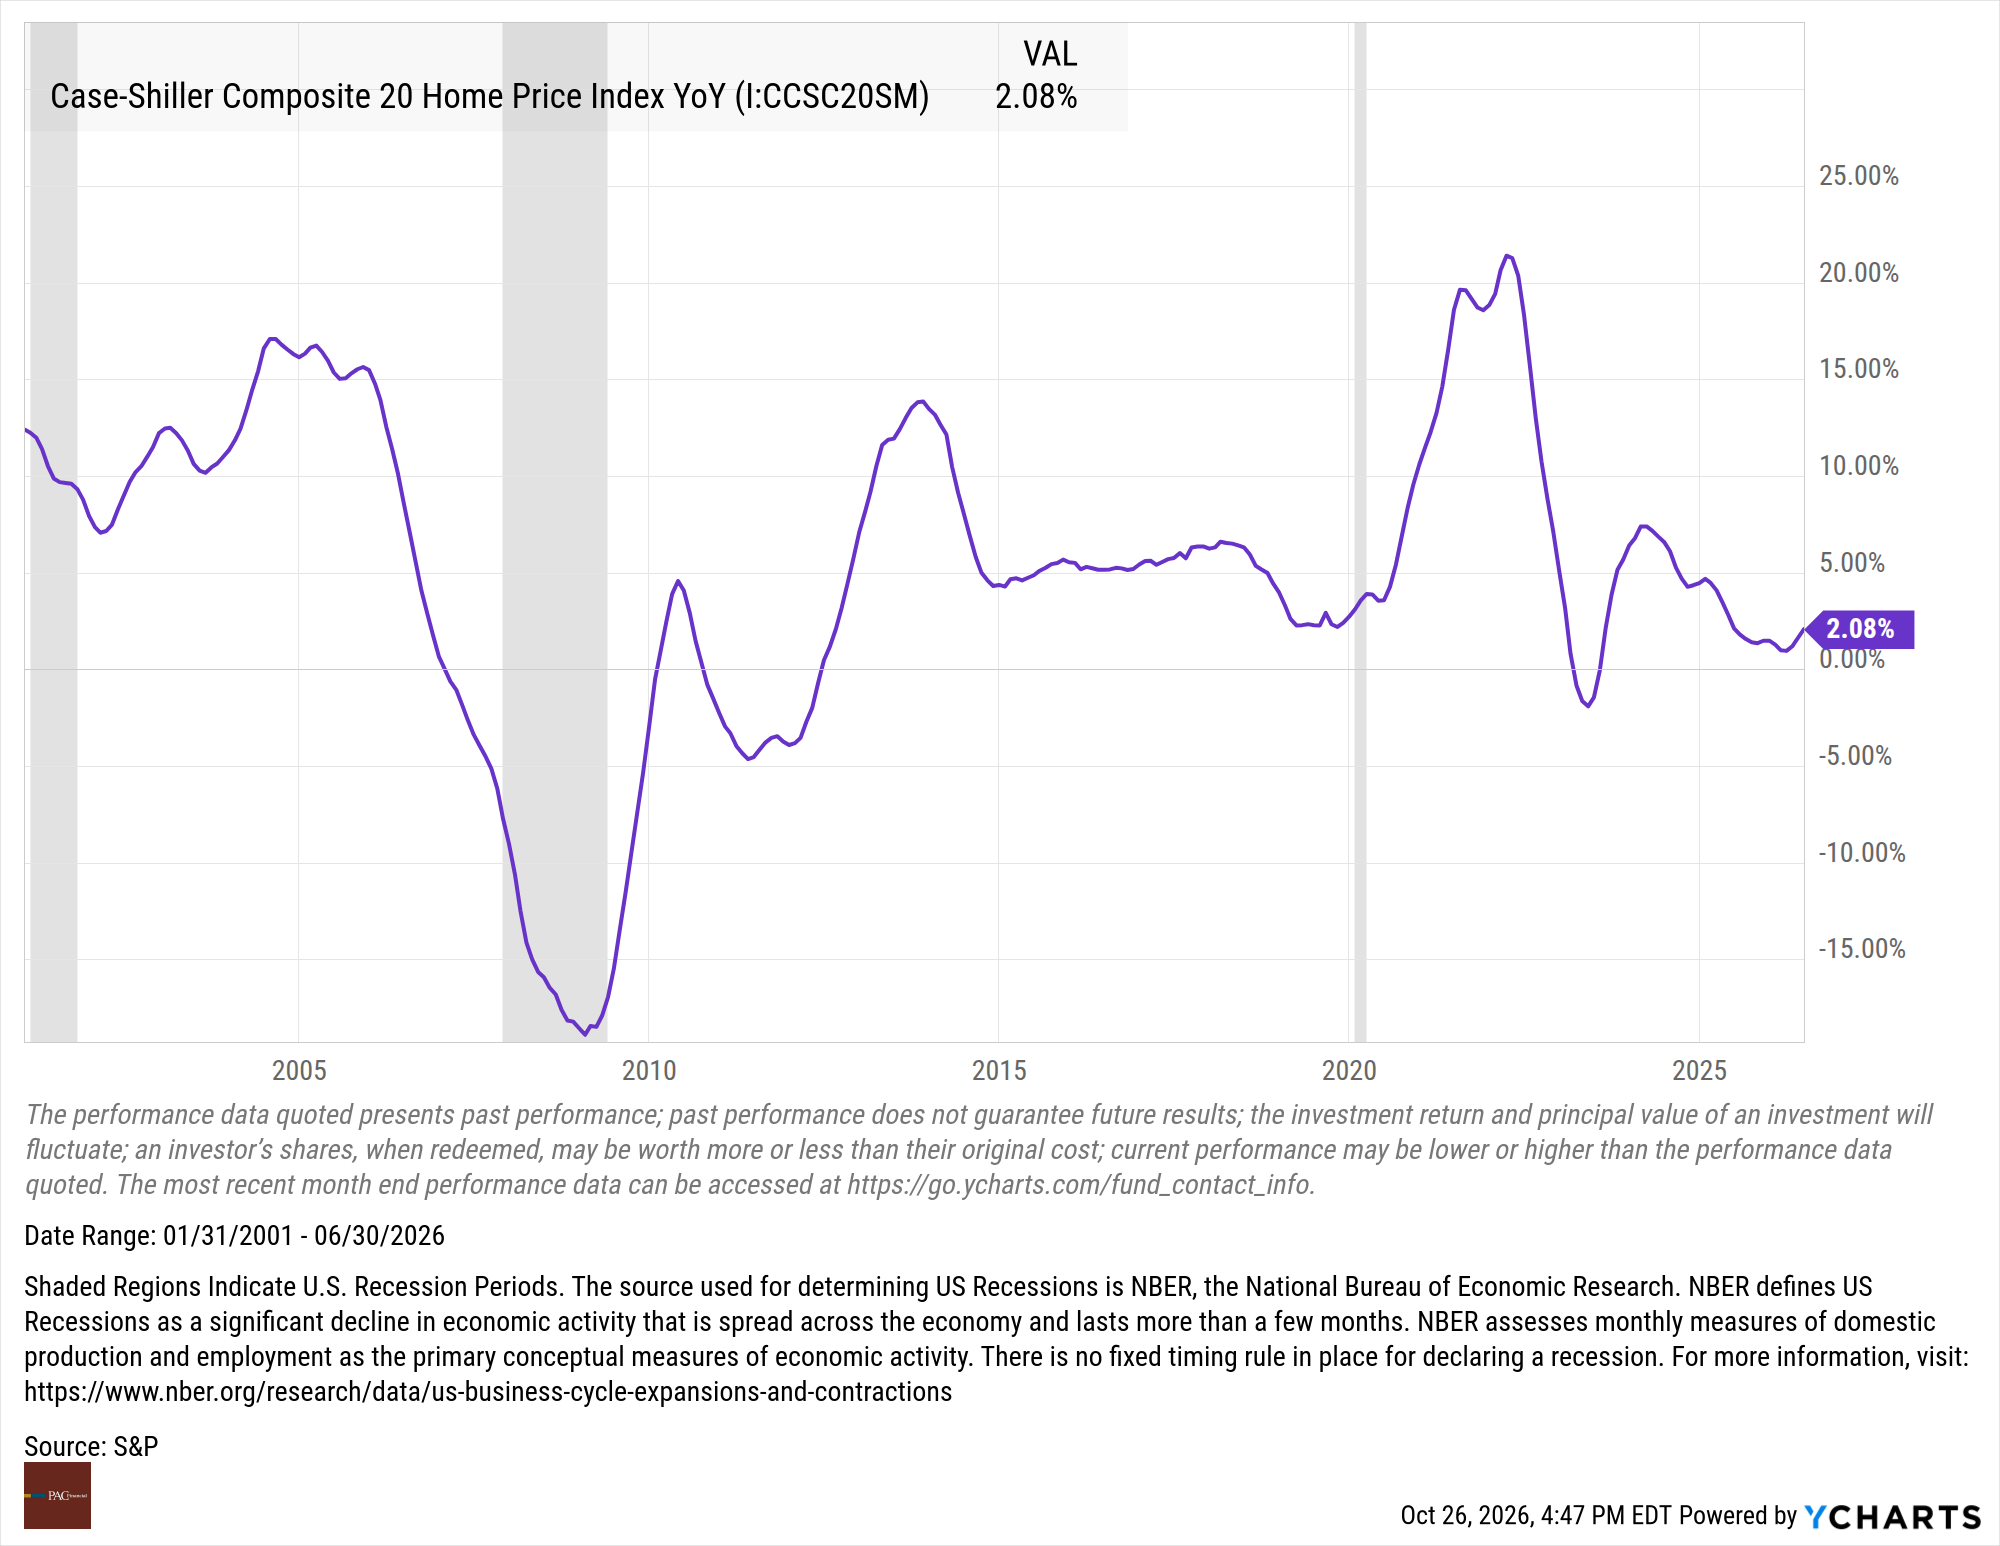
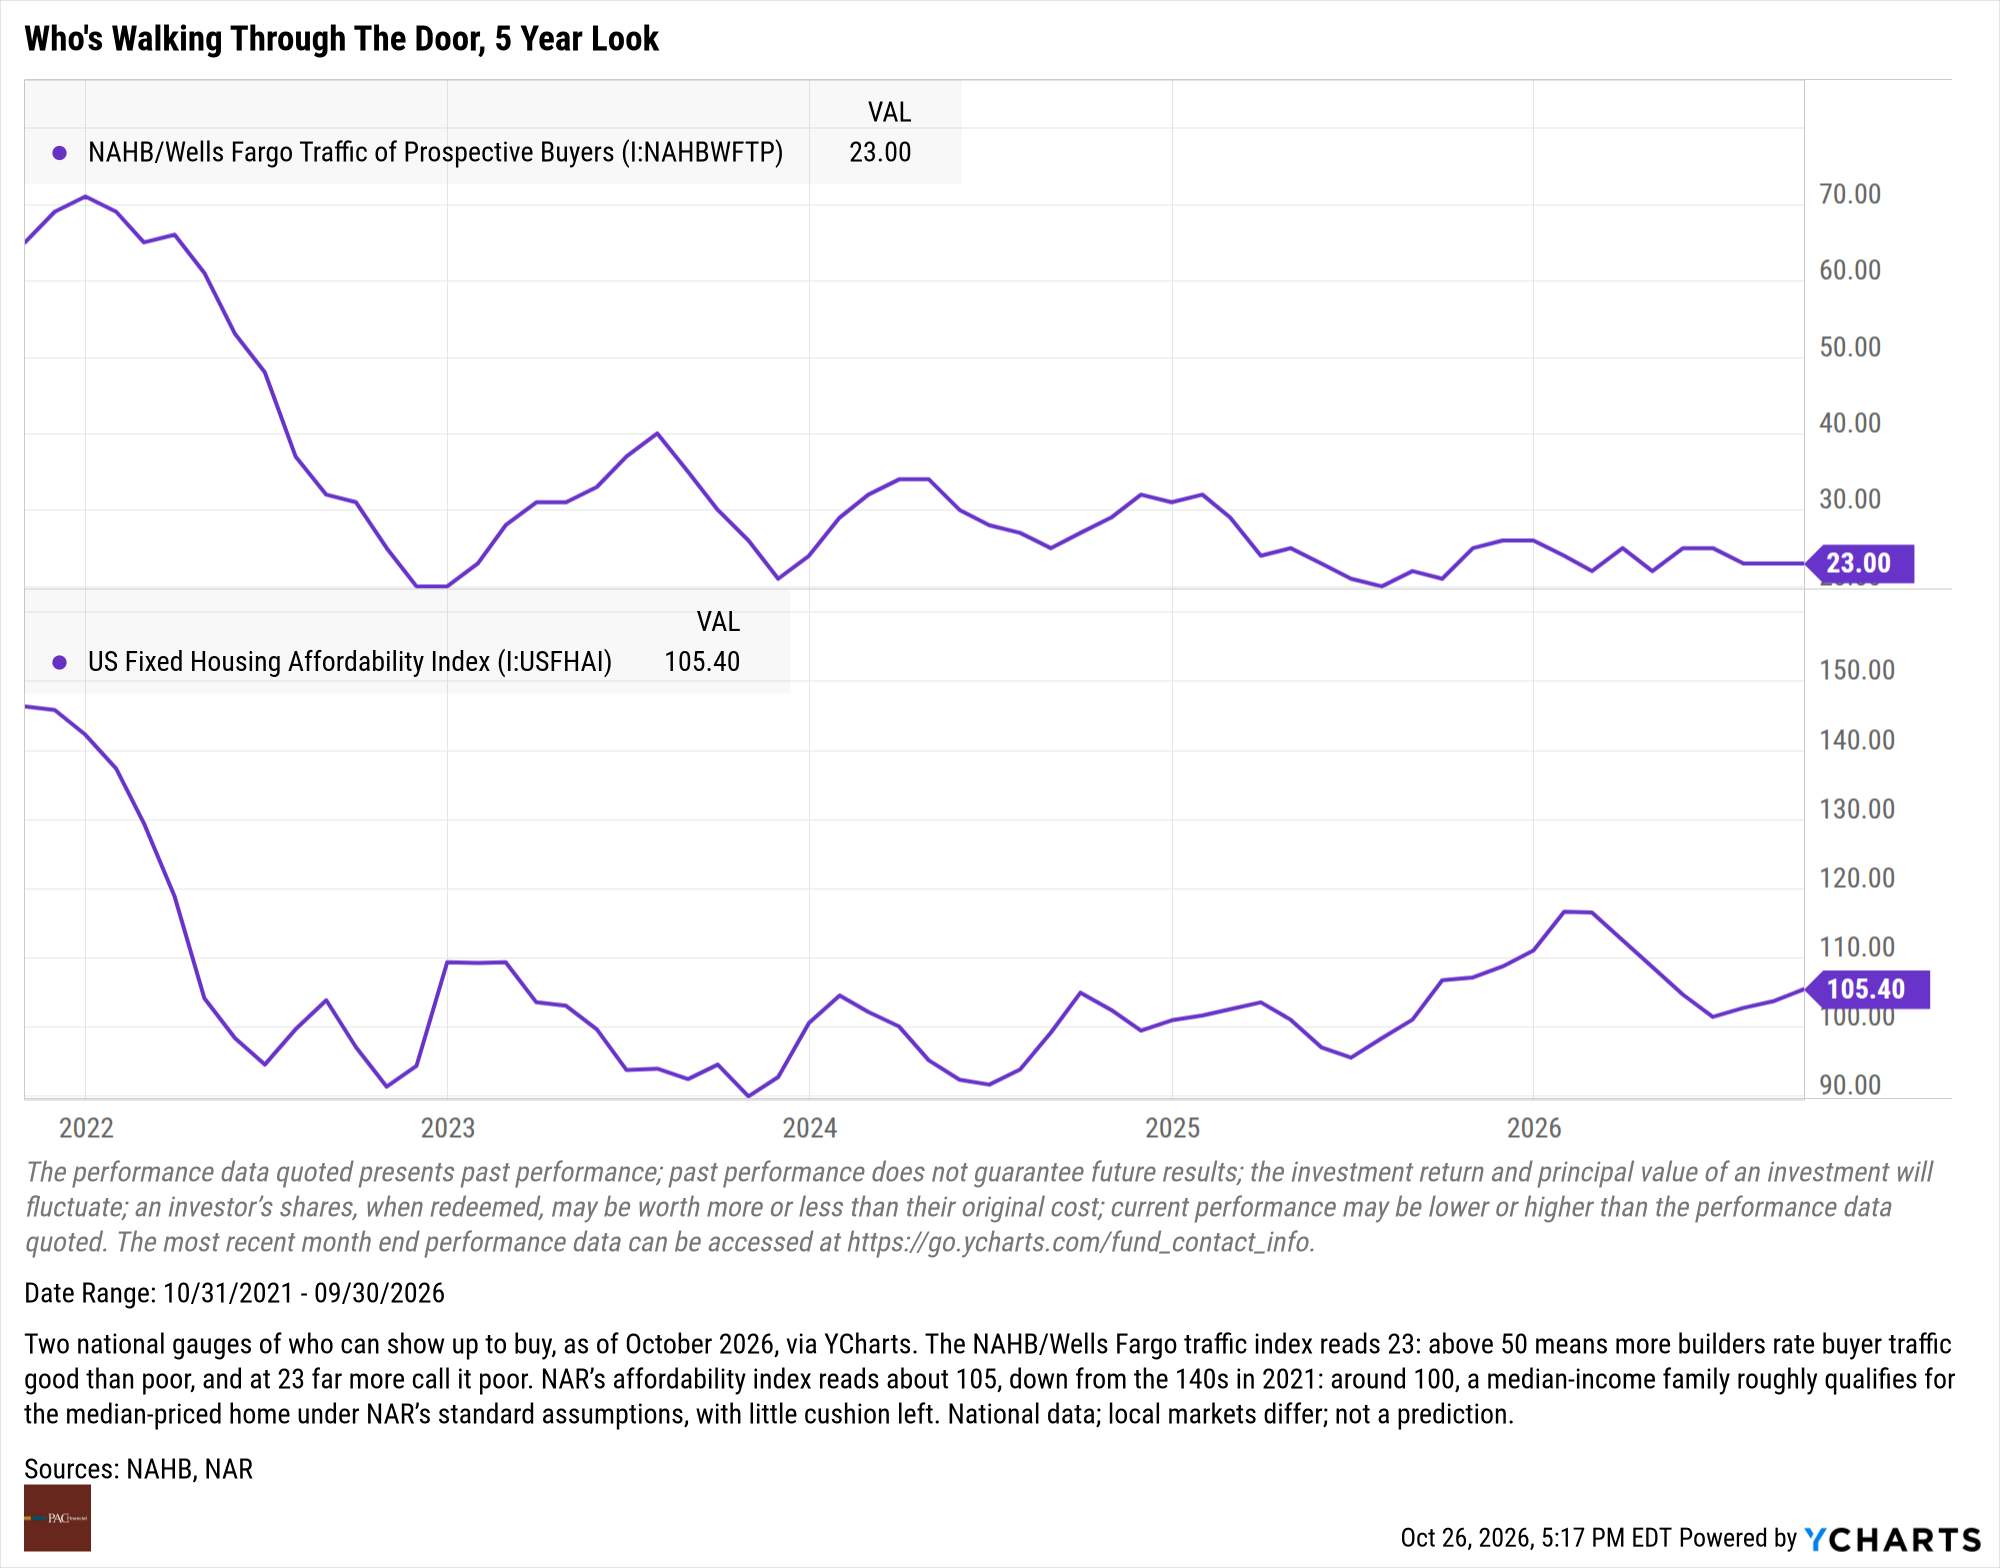
A few numbers, each as of its most recent published reading, via YCharts from the named sources. The average 30-year mortgage rate is about 7.3 percent (Freddie Mac, October 2026). Builder-reported traffic of prospective buyers sits at 18, down from 23 a year earlier (NAHB/Wells Fargo, October 2026). Existing home sales are running at roughly a 4 million annual pace (National Association of Realtors, September 2026). National home prices are rising about 2 percent year over year, a slower pace than the year before (S&P Case-Shiller Composite 20, June 2026, the most recent published reading). None of this predicts anything. It describes the market as it stands.
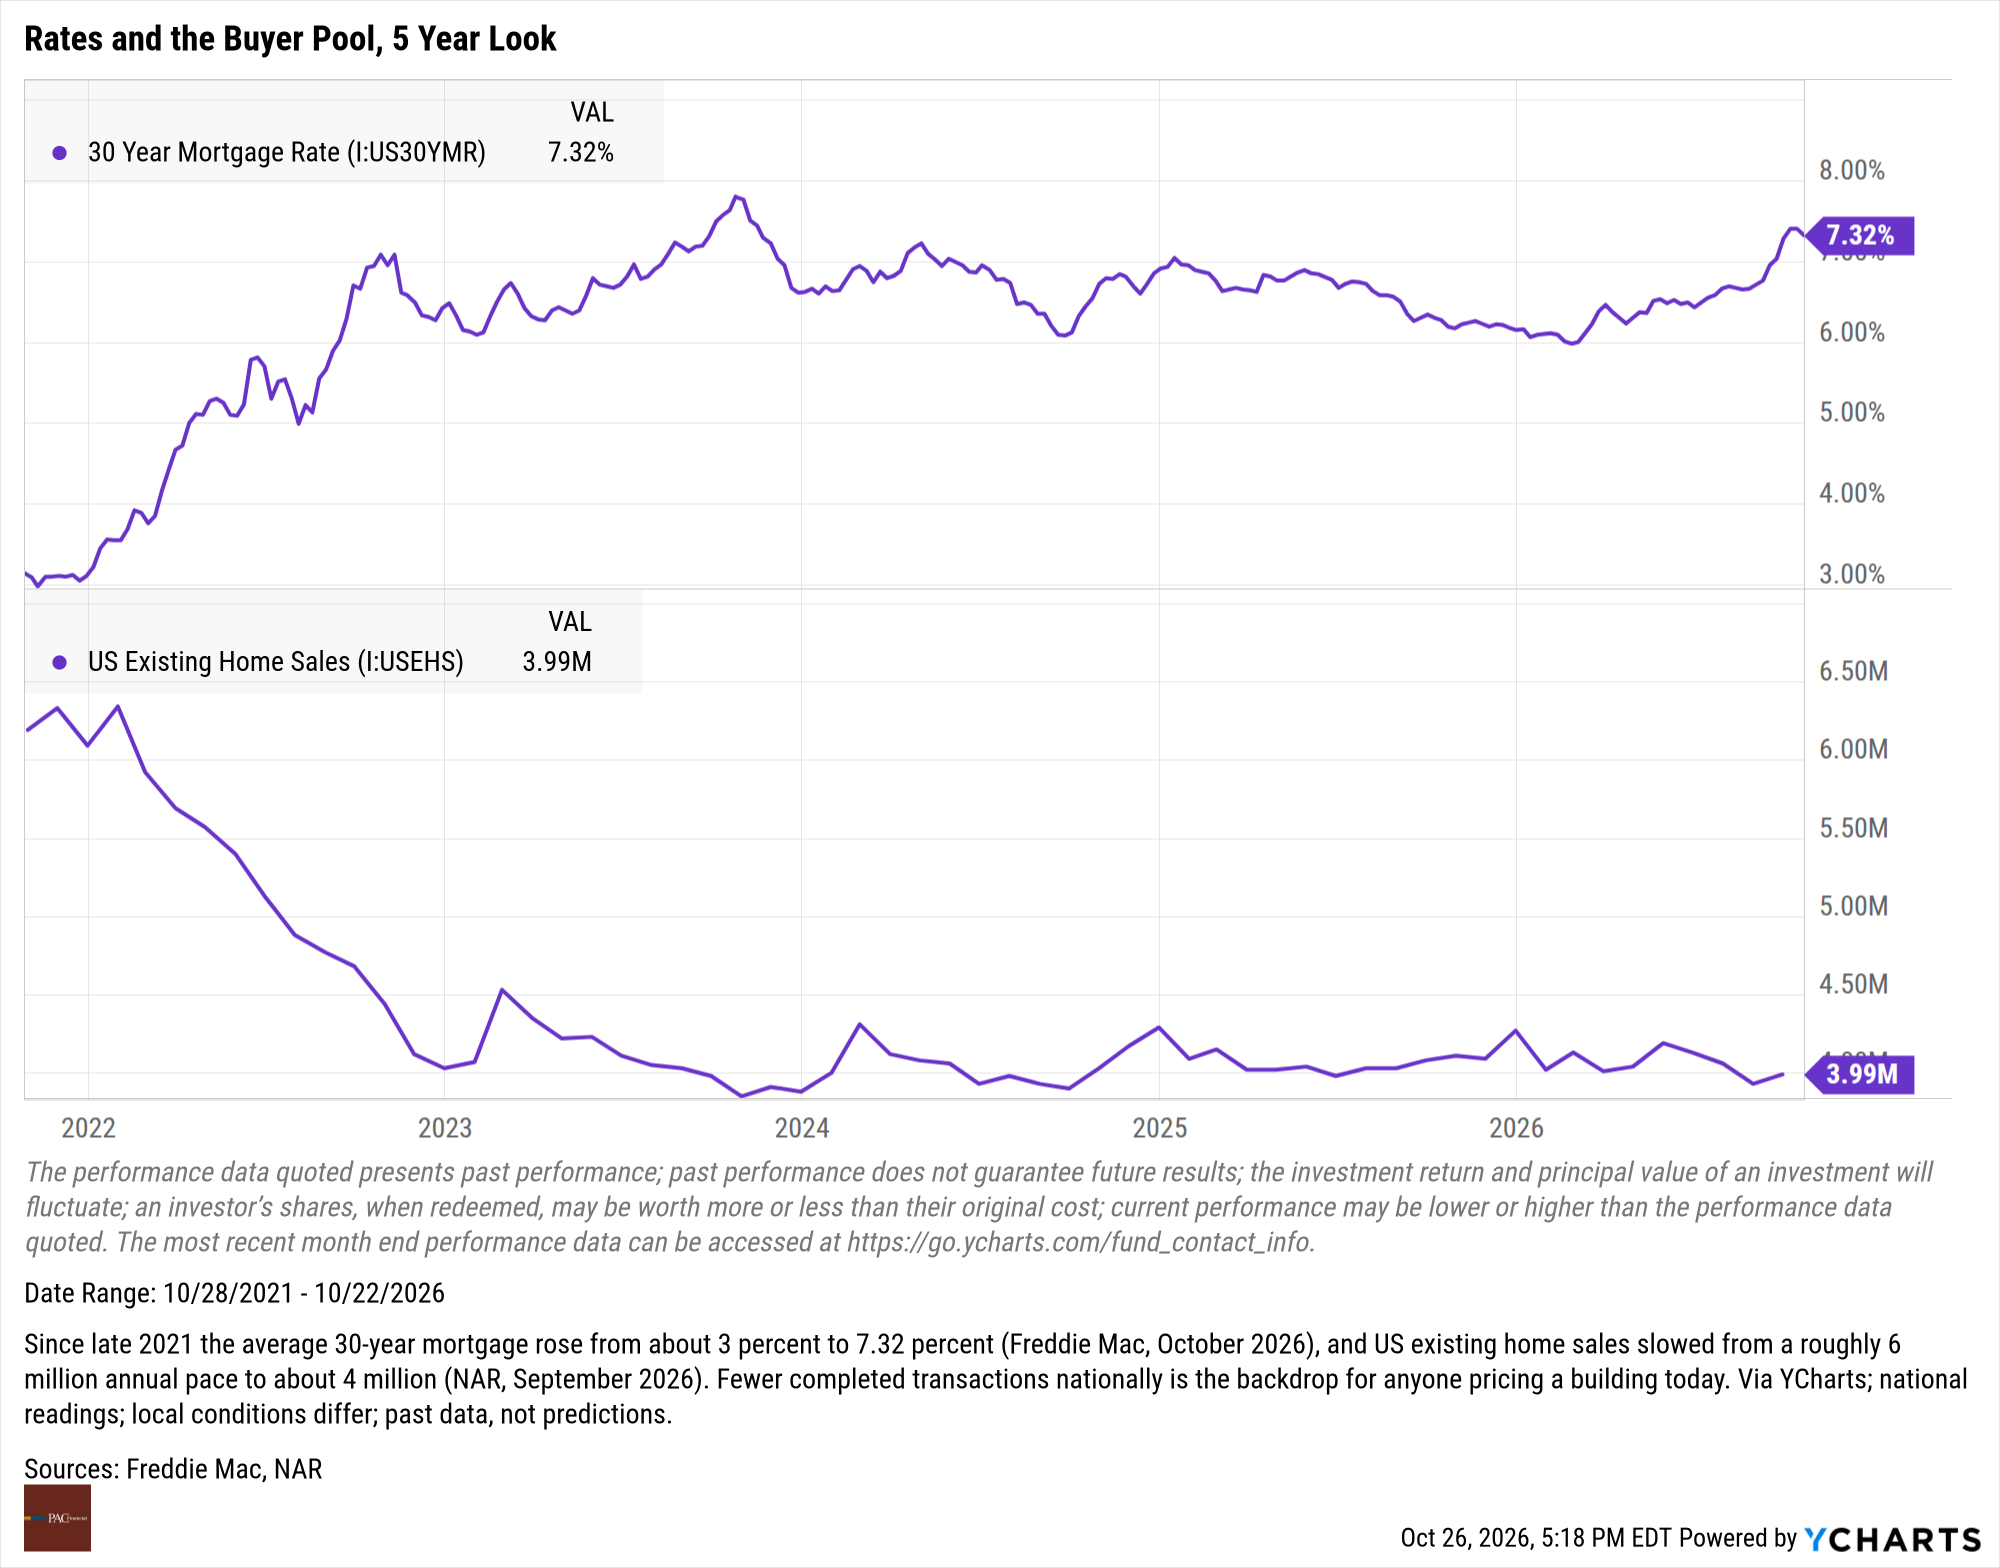
Why do 7 percent mortgages matter to a landlord who isn't buying anything?
Because selling is a two-party event. When the financing cost of every potential buyer rises, fewer buyers qualify at a given price, and the NAHB traffic reading above is one national measure of that thinning. What follows for any individual sale varies with the building, the block, and the buyer. The national picture simply describes fewer active buyers and a slower pace than the years many owners still have in their heads.
Are property values falling in Central Pennsylvania?
Nationally, prices are still rising, just more slowly: about 2 percent year over year as of the most recent published Case-Shiller reading, versus much faster growth in earlier years. Local markets differ, Central Pennsylvania included, and we do not forecast prices, here or anywhere. What slower growth and thinner buyer traffic have generally meant together is time: turning a building into money has tended to take longer in markets like this one, though local experience varies. Time is something an owner can plan around.
What should an owner actually do with this?
Nothing dramatic. Three calm things. Know your own debt schedule: which notes reset, and when. Plan as if a sale would take longer than it would have a few years ago. And hold liquidity beside the buildings, which reduces the odds of ever having to sell into a slow market on someone else's deadline; it cannot remove them, but it moves the decision back onto your schedule. Whether to sell at all is your decision, and what a sale would mean for your taxes belongs with your tax professional; we sit at the same table. If a sale is on your mind, read who to call first before selling a rental property.
| Indicator | Reading | As of |
|---|---|---|
| 30-year mortgage rate (Freddie Mac) | About 7.3% | October 2026 |
| Traffic of prospective buyers (NAHB/Wells Fargo) | 18, down from 23 a year earlier | October 2026 |
| Existing home sales pace (NAR) | Roughly 4.0M annualized | September 2026 |
| Case-Shiller Composite 20 (S&P) | About +2% year over year | June 2026 |
| Housing affordability index (NAR) | About 105 | September 2026 |
Via YCharts from the named sources. Readings change monthly and are not predictions.
Tucker Nicholas is a Private Wealth Advisor at PAC Financial in Harrisburg, Pennsylvania. Call (717) 564-6400, ext. 181, and bring your tax professional into it from the first call.
This material is for general information only and is not investment, tax, or legal advice, nor a recommendation of any specific security or strategy. Investing involves risk, including possible loss of principal. Past performance does not guarantee future results. PAC Financial does not provide tax or legal advice; consult a qualified tax professional about your situation. PAC Financial provides investment advisory and brokerage services and receives compensation for those services; depending on the services selected, accounts are advisory or brokerage, and the differences and costs of each are explained in writing before any account is opened. Securities and advisory services offered through Osaic Wealth, Inc., member FINRA/SIPC. PAC Financial and Osaic Wealth, Inc. are separately owned and other entities and/or marketing names, products or services referenced here are independent of Osaic Wealth, Inc. Check the background of your financial professional on FINRA's BrokerCheck. Tucker P. Nicholas is registered in PA, CO, and DE. PAC Financial, 5291 Devonshire Road, Harrisburg, PA 17112, (717) 564-6400.